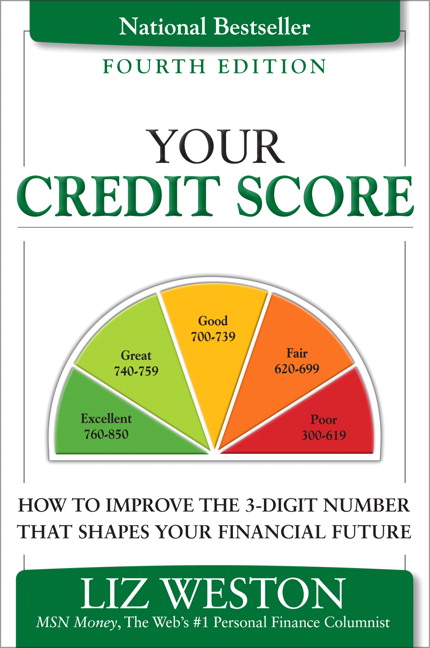
• Skip to main content
  • Skip to primary sidebar

Ask Liz Weston

Get smart with your money

  • About
  • Newsletter
  • Liz’s Books
  • Speaking
  • Disclosure
  • Contact

Credit Reports

Wednesday’s need-to-know money news

June 19, 2013 By Liz Weston

Passenger airplane landing on runway in airport.The myth of open houses, the credit report you never knew about and how to avoid being squeezed by airlines.

The Credit Report You Haven’t Seen Yet

How “alternative credit data” could help you get approved at lower rates.

Cyber-thieves: More Tips on How to Protect Yourself From Credit Card Theft

Protecting you and your credit from cyber-theft.

Are Open Houses a Waste of Sellers’ Time?

Open Houses are not only a waste of time; they could be an open invitation to thieves.

The Worst Fee-Greedy Airlines

From bag fees to charging to make reservations by phone, airlines are determined to squeeze as much money out of passengers as possible.

When to Buy a Mutual Fund

There’s money to be made in mutual funds, if you have the patience.
Filed Under: Liz's Blog, Saving Money Tagged With: airline fees, airlines, Credit Bureaus, Credit Reports, home sale, Identity Theft, travel

The best place to get your credit reports, scores

June 17, 2013 By Liz Weston

Dear Liz: I want to see all three of my credit reports with scores and fix some things on there that could be in error. What site do you recommend to get all three with scores?

Answer: You have a federally mandated right to see your credit reports once a year, and you can access those reports at http://www.annualcreditreport.com. That is the one and only federally authorized site. There are plenty of look-alikes, so make sure you get to the right place. Each of your three reports will include links that will allow you to dispute errors.

When you access your reports, you may be offered credit scores either for a fee or as an inducement to sign up for credit monitoring. Typically, these scores are not the FICO scores that most lenders use. If the word “FICO” is not in the name of the credit score being offered, it’s not an actual FICO score.

To get your FICOs, you’ll need to go to MyFico.com. Currently, you can buy two of your three FICOs — the ones from Equifax and TransUnion — for $19.95 each. Experian has announced it will soon offer FICOs through MyFico.com as well.

Filed Under: Credit Scoring, Q&A Tagged With: AnnualCreditReport.com, Credit Bureaus, Credit Reports, Credit Scores, credit scoring, FICO, FICO scores, MyFico.com

Wednesday’s need-to-know money news

June 12, 2013 By Liz Weston

FinancesFather knows best, careers that simply aren’t worth the money and the double-edged sword of frugality.

Listen to Your Father! Old-School Money Tips for Today

Financial advice that stands the test of time.

The Best and Worst Careers to Go Into Debt For

If you want to see your work in print, become an advertiser, not a reporter.

Credit Expert Answers 7 Burning Personal Finance Questions

Including tips on how to improve your credit score.

When Frugality Goes Too Far

Growing your own vegetables is a great idea. Spending $3500 on a vegetable garden is not.

Overdraft Fees Cost Bank Customers Hundreds of Dollars a Year

The Consumer Financial Protection Bureau found overdrawing their accounts cost customers an average of $225 per year.

Filed Under: Liz's Blog Tagged With: banking, college costs, college debt, courtesy overdraft, Credit Cards, Credit Reports, Credit Scores, FICO, FICO scores, financial advice, overdraft fees, Student Loans

Thursday’s need-to-know money news

June 6, 2013 By Liz Weston

YCS4 coverGood credit, stolen credit and ways to save on travel to the vacation home you should have purchased when mortgage rates were historically low.

Five Reasons Why You Can’t Ignore Your Credit

While living debt free is a good thing, living credit free can have unforeseen and expensive consequences.

Here’s Everything We Know About The Rakuten/Buy.com Credit Card Breaches

If you’ve shopped at the online marketplace recently, you should pay very close attention to your statements.

26 Secrets to Save on Travel

Flying on a Saturday afternoon may not sound like fun, but it could save you big bucks.

Farewell 3% Mortgage Rates

Job gains and an improving economy signal the end of historically low mortgage rates.

Filed Under: Liz's Blog Tagged With: Credit Cards, Credit Reports, Credit Scores, credit scoring, database breaches, FICO, FICO scores, mortgage refinancings, mortgages, travel

Forgotten credit card trashes scores

May 5, 2013 By Liz Weston

Dear Liz: My husband and I are in the process of refinancing our mortgage. I just received my credit report in the mail, and my score was 724. The report indicated that a delinquency resulted in my less-than-stellar score. When I went to the credit bureau site to see where the problem was, I saw that I had a $34 charge on a Visa last year. I rarely use that card, so I did not realize that I had a balance. As a result, I had a delinquent balance for five months last year. I am sick about this, as I always pay my bills on time. To think that my credit score was affected by something so insignificant is really bumming me out. Is there anything I can do to fix this?

Answer: You can try, but creditors are often reluctant to delete true negative information from your credit files. That’s why it’s so important to monitor all of your credit accounts, and to consider signing up for automatic payments so that this doesn’t happen again.

You should know that your mortgage lender won’t look at just one credit score when evaluating your application. Typically, mortgage lenders would request FICO credit scores from each of the three bureaus for both you and your husband, then use the lower of the two middle scores to determine your rate. Even if 724 did turn out to be the lowest of the six scores, you should still get a decent rate, since that’s considered a good score.

Filed Under: Credit & Debt, Credit Cards, Credit Scoring, Q&A, Real Estate Tagged With: Credit Bureaus, Credit Cards, Credit Reports, Credit Scores, credit scoring, debt collection, FICO, FICO scores

Should you pay to boost your credit scores?

March 11, 2013 By Liz Weston

Dear Liz: I’ve seen advertisements for services that promise to help you raise your credit score by the exact number of points you need to qualify for a good mortgage rate. Are these services worth the money?

Answer: There’s one thing you need to know about these services: They don’t have access to the actual FICO formula, which is proprietary. So what they’re doing is essentially guesswork.

They may suggest that you can raise your score a certain number of points in a certain time frame, but the FICO formula isn’t that predictable. Any given action can have different results, depending on the details of your individual credit reports.

Rather than pay money to a firm making such promises, use that cash to pay down any credit card debt you have. Widening the gap between your available credit and your balances can really boost your scores. Other steps you should take include paying your bills on time, disputing serious errors on your credit reports and refraining from opening or closing accounts.

Filed Under: Credit & Debt, Credit Cards, Credit Scoring, Q&A Tagged With: Credit Bureaus, Credit Cards, Credit Reports, Credit Scores, credit scoring, FICO, FICO scores, mortgages

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 6
  • Page 7
  • Page 8
  • Page 9
  • Page 10
  • Go to Next Page »

Primary Sidebar

Search

Copyright © 2026 · Ask Liz Weston 2.0 On Genesis Framework · WordPress · Log in